

Detalles
| The objective of this guide is to support the implementation activities of preparers and others who use or analyse ESRS reports, in this case specifically on value chain information in accordance with the requirements of Articles 19a or 29a of Directive 2013/34/EU (referred to as the "Accounting Directive") as amended following the Corporate Sustainability Reporting Directive (referred to as the "CSRD"). 9. The content of this document has been developed on the basis of the July 2023 delegated act. |
Recursos relacionados
The role of true cost accounting in guiding agrifood businesses and investments towards sustainability
The current economic system, and in particular the way we fail to measure, value and report on the impact of…
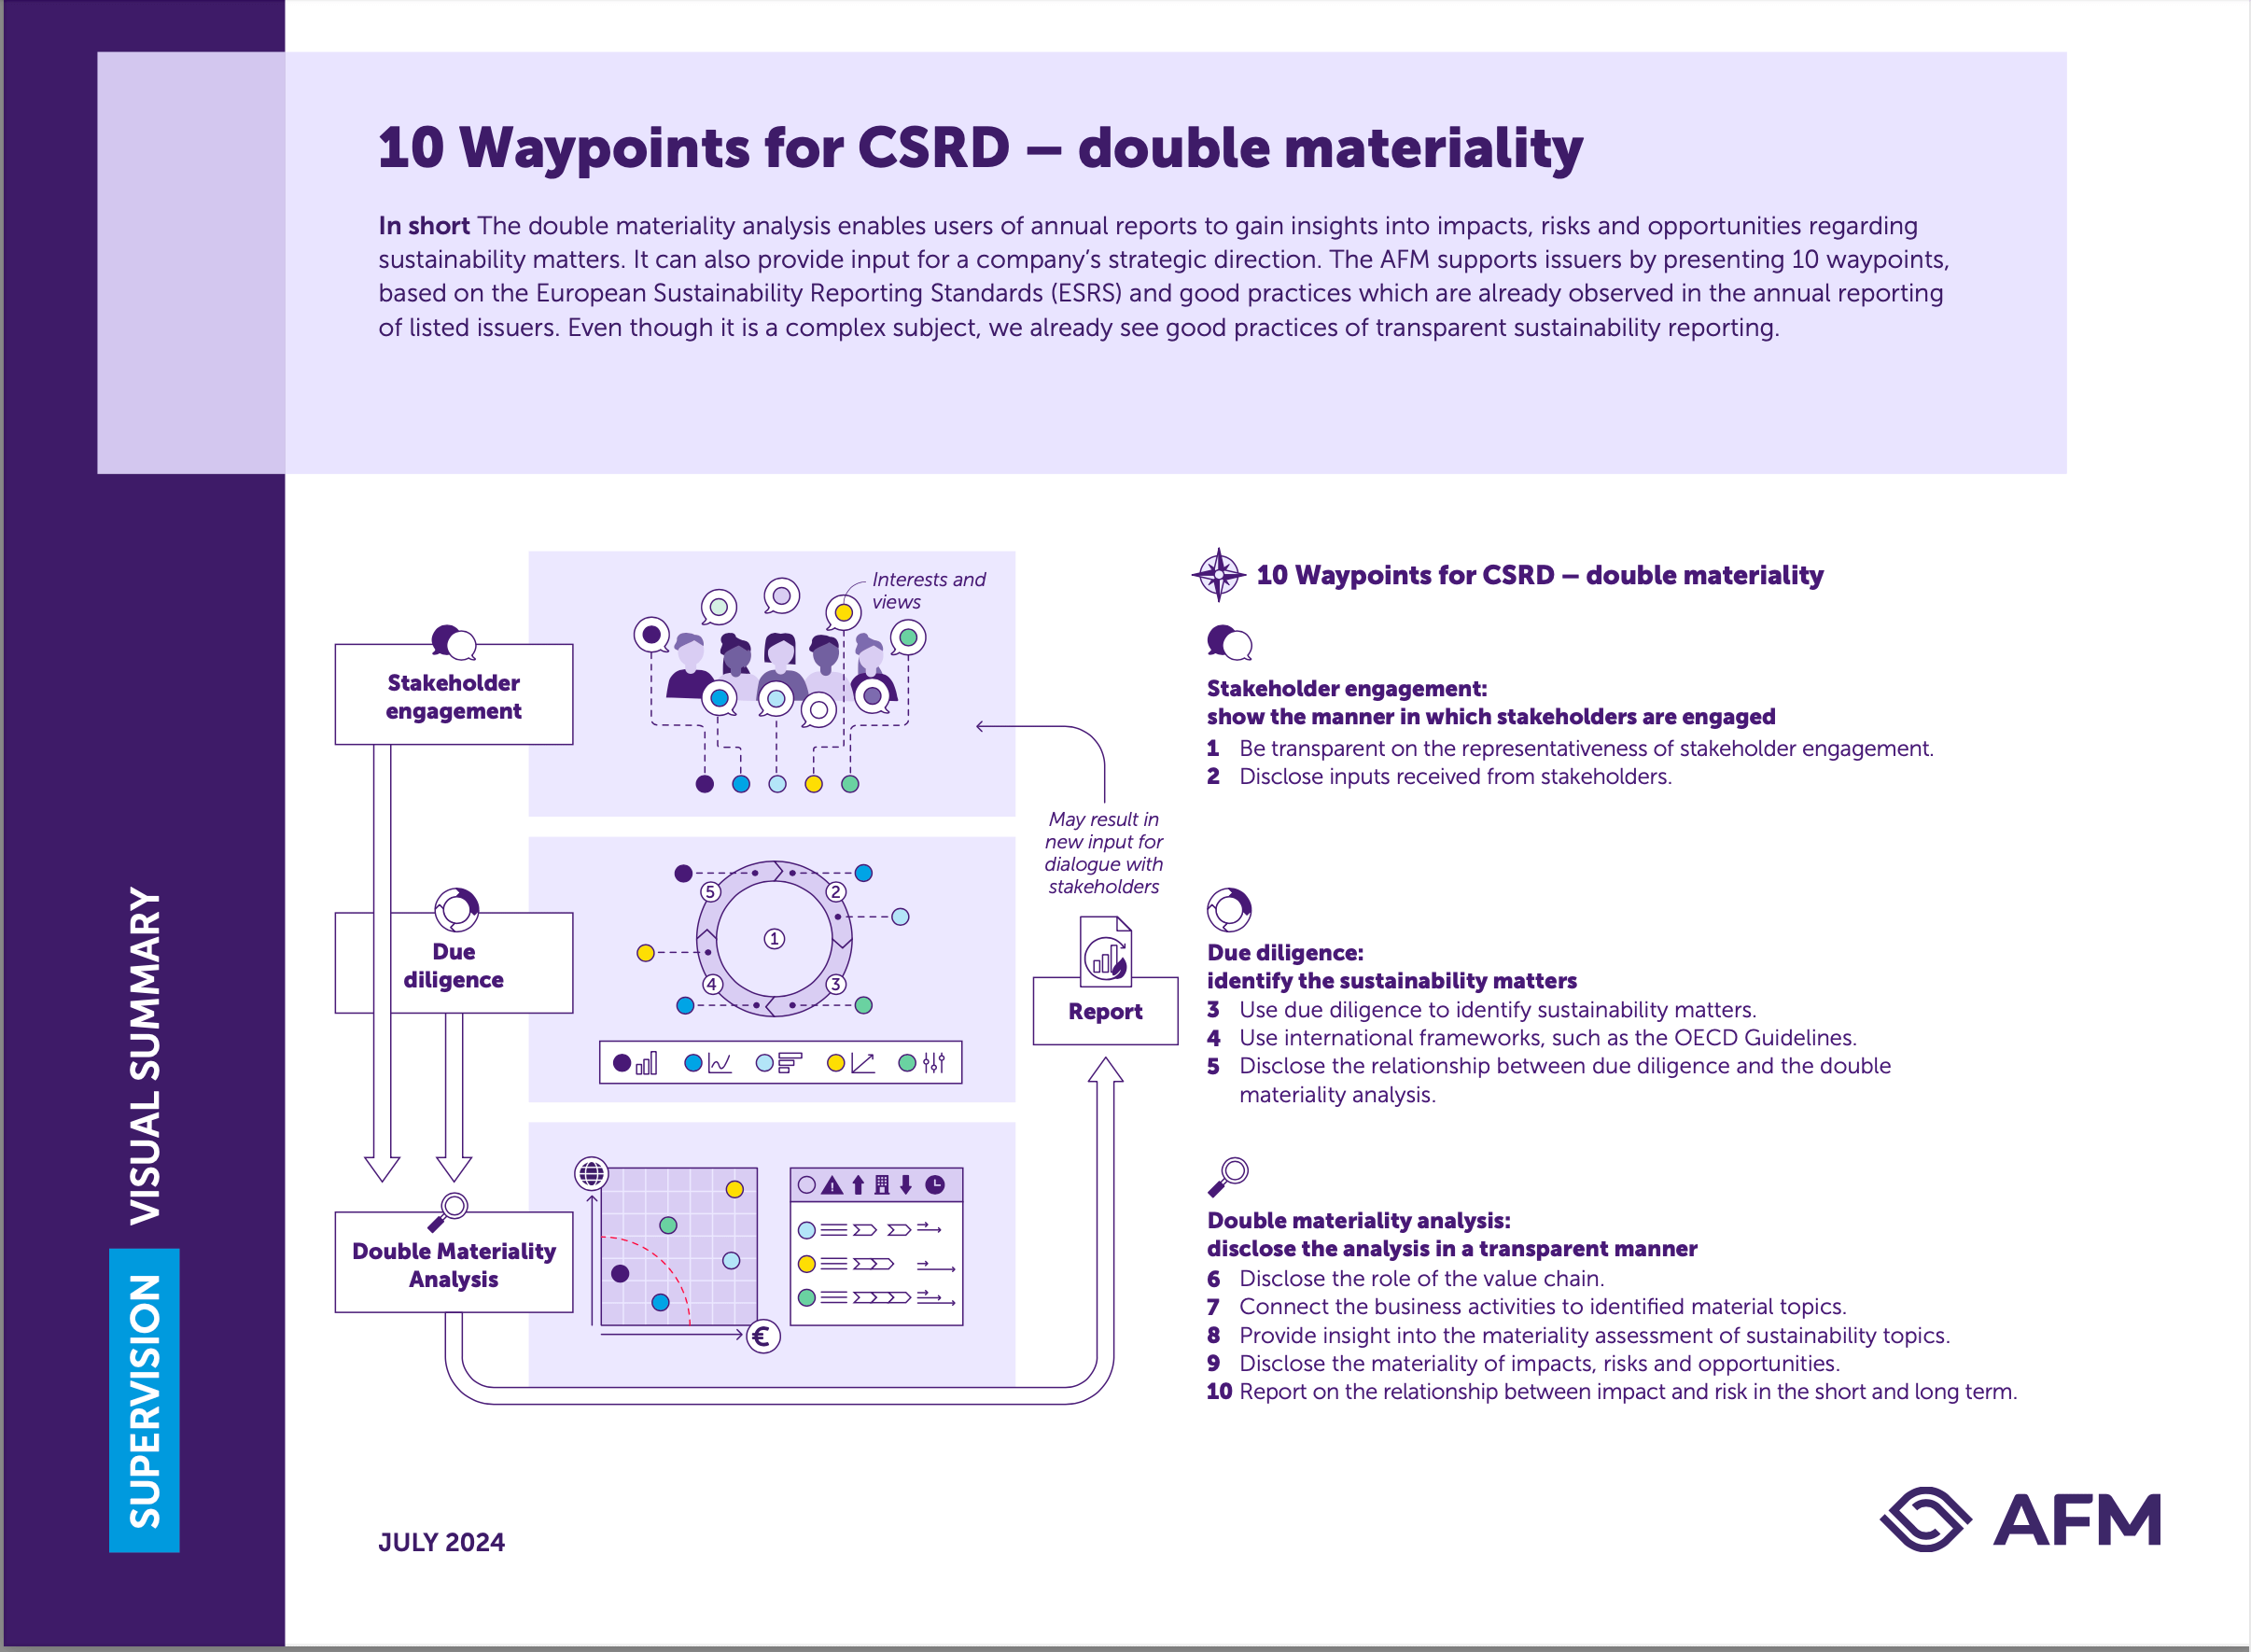
10 Waypoints for CSRD – double materiality
Dual materiality analysis plays a key role in the Corporate Sustainability Reporting Directive (CSRD ) that came into force for…
Improving climate and biodiversity outcomes through restoration of forest integrity
This publication maps out the potential restoration zones. Research and practice so far has focused mainly on the reforestation of…